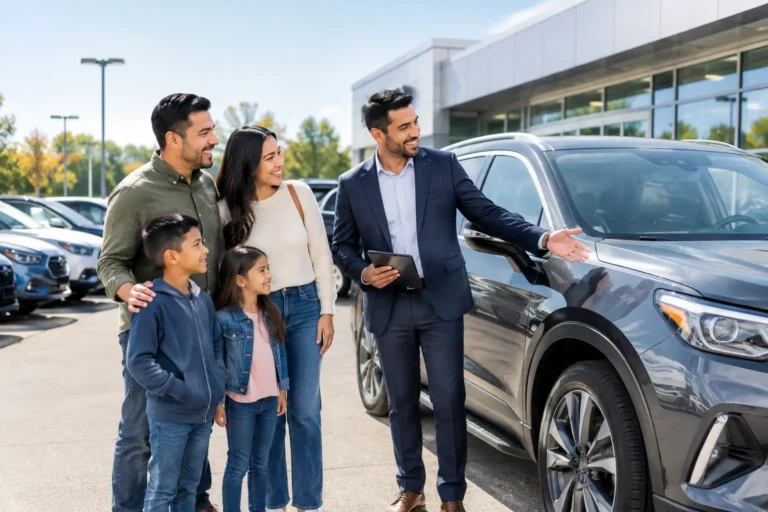
A car payment has to work on more than the day you drive off the lot. It has to fit the weekly commute, school drop-offs, grocery runs, tolls, fuel, and everything else that comes with life in North Jersey. That is why North Jersey car financing should start with a real budget and a clear plan, not a guess based on a payment number you saw online.
At ACI Auto Sales in Elizabeth, the goal is straightforward: help you match a dependable used vehicle with a financing path that makes sense for your situation. Whether you have established credit, limited history, a past credit challenge, or were turned down elsewhere, the right next step is to review your options and focus on a vehicle you can comfortably keep.
Start With the Monthly Payment You Can Handle
Most shoppers begin with the vehicle price. That matters, but the monthly payment is usually where the decision becomes real. Before you shop, look at what remains after rent or mortgage payments, utilities, food, phone bills, child care, and other regular expenses. Leave room for fuel, registration, routine service, and unexpected costs too.
Pick a payment range that feels manageable without stretching every month. Being approved for a higher amount does not automatically mean it is the right amount to borrow. A practical used sedan may leave more breathing room in your budget than a larger SUV with more features. On the other hand, a family that needs three rows or a commuter who drives long distances may get more value from choosing the vehicle that truly fits daily needs.
The best deal is not always the lowest advertised price. It is the car, term, down payment, and monthly payment that work together.
How North Jersey Car Financing Usually Works
Financing means a lender provides the money to buy the vehicle, and you repay that amount over an agreed term with interest. Your approval terms can be shaped by your credit profile, income, debt obligations, down payment, vehicle price, and the lender’s requirements.
A stronger credit history may open the door to more lender options or a lower interest rate. That does not mean buyers with fair credit, no credit, or credit challenges should sit out the process. Many customers need a different financing route, a larger down payment, a more affordable vehicle, or documentation that shows stable income. There can still be a realistic way forward.
At a used-car dealership, financing may include prequalification through Capital One, participating outside lenders, or Buy Here Pay Here options where applicable. Each path serves a different need. Prequalification can give eligible buyers an early view of potential financing without starting the conversation blindly. Outside lenders may offer terms based on their own lending guidelines. Buy Here Pay Here can be worth discussing for customers who need a more flexible approach after traditional financing has not worked out.
Terms, rates, payments, and approvals vary by applicant and vehicle. The smart move is to get clear numbers for your actual deal rather than assume a generic online calculator tells the full story.
Prequalification Gives You a Better Starting Point
Prequalification is useful because it moves the conversation from “What might I qualify for?” to a more focused vehicle search. It can help you narrow your price range and spend more time looking at cars that fit your likely payment.
It is not the same as a final approval. Final financing can depend on verifying information, selecting a vehicle, lender review, and other conditions. Still, it is a strong first step for shoppers who want direction before visiting the lot.
Down Payment Can Change the Whole Deal
A down payment reduces the amount you need to finance. That can lower the monthly payment, reduce total interest paid over time, or help make a lender’s terms more workable. Even a modest amount can make a difference.
Do not drain every dollar you have just to make a larger down payment, though. Keeping a small emergency cushion is sensible. If you have a trade-in, its value may also affect the amount you finance, depending on its condition and payoff balance.
Bring the Right Information and Keep the Process Moving
Financing goes faster when you are ready to verify the basics. Requirements can vary by lender, but most buyers should expect to provide identification, proof of income, proof of residence, and information about a trade-in if they have one. If you receive direct deposit, pay stubs or bank statements may help document income. Self-employed buyers may need additional records.
Be accurate on your application. Income, address, employment, and monthly housing information should match your documents. Small inconsistencies can slow down a deal that might otherwise move quickly.
If you are unsure what to bring, call before visiting and ask. A short conversation can save a second trip. Spanish-speaking customers can ask for bilingual assistance as well – Hablamos Español.
Choose the Vehicle Before You Choose the Story
It is easy to get attached to a specific vehicle before knowing whether it fits your financing plan. Start with your real needs instead. Consider passenger space, cargo room, your work commute, parking, and how long you expect to keep the vehicle.
A commuter traveling between Elizabeth, Newark, and the rest of the metro area may prioritize fuel economy and comfortable highway driving. A growing family may need a reliable SUV with room for car seats and weekend errands. A contractor or delivery worker may need a truck or van that supports the job. There is no single best vehicle, only the best match for your work, family, and budget.
Once you identify a few options, confirm availability before heading out. Used inventory changes quickly. Ask about the vehicle, schedule a test drive, and review the numbers on the specific car you want. That keeps the process honest and avoids wasting time on a vehicle that has already sold.
Watch the Trade-Offs in Loan Terms
A lower monthly payment can look attractive, but it often comes from extending the loan term. A longer term may give your budget more room now, while also increasing the total interest you pay over the life of the loan. A shorter term can reduce total interest but raise the payment.
Neither option is automatically right. If the shorter term makes your budget too tight, the lower payment may be the wiser choice. If you can comfortably afford a higher payment and want to pay less interest overall, a shorter term may be worth considering. Ask to see the payment and total financing cost under more than one term so you can compare the trade-off clearly.
Also pay attention to the full out-the-door picture, not just the payment. A clear buyer asks what is included, how much is due at signing, what the term is, and what the estimated payment will be. Straight answers make better decisions.
What to Do If You Were Denied Before
A previous denial does not define every future financing decision. Different lenders use different guidelines, and your situation may have changed since the last time you applied. You may have more income, a different down payment amount, less debt, or a vehicle choice that better matches lender requirements.
Do not apply everywhere without a plan. Start by discussing your situation honestly with a dealership that offers multiple financing paths. Be upfront about your budget, income type, credit concerns, and down payment. That allows the team to focus on realistic options instead of pushing you toward a payment that does not make sense.
If the numbers are not right yet, waiting, saving more for a down payment, or choosing a lower-priced vehicle can be the better move. The point is to leave with transportation you can maintain, not a payment that creates pressure every month.
Take the Next Step With a Clear Plan
Start by browsing available used cars that fit your needs, then get prequalified or submit a financing application to understand your potential path. If you already have a vehicle in mind, confirm it is available and schedule a test drive. Bring your basic documents, ask direct questions, and compare terms before you sign.
The right car should make your day easier, not your budget harder. When you are ready to look at real options, take the next step and get the numbers that fit your life.